
Most people spend decades asking one question about retirement: how much can I save? Then retirement arrives and the question changes: how do I take the money out? The answer matters more than most retirees expect. Two people with the same $300,000 saved can end up with very different amounts to spend, depending only on which account they draw from first, and in which year.
A tax-efficient withdrawal plan is simply a plan for the order you take money from your accounts, year by year, so that the total tax across your whole retirement is as low as possible. It is not about paying the least tax this year. It is about paying the least tax over twenty or thirty years, while keeping Medicare premiums down and leaving as much as possible to a spouse or heirs. This guide works through the 2026 rules, with the actual figures, so you can see how the pieces fit together.
The Numbers at a Glance
- 2026 tax brackets: seven rates, 10, 12, 22, 24, 32, 35 and 37 percent. For a single filer the 22 percent rate starts at $50,400 of taxable income; for a married couple filing jointly it starts at $100,800, according to IRS Revenue Procedure 2025-32.
- 2026 standard deduction: $16,100 for a single filer, $32,200 for a married couple filing jointly and $24,150 for a head of household, according to IRS Revenue Procedure 2025-32.
- Capital gains at 0 percent: long-term gains are taxed at 0 percent while total taxable income stays at or below $49,450 for a single filer and $98,900 for a married couple filing jointly in 2026, according to IRS Revenue Procedure 2025-32.
- RMD ages: required minimum distributions start at 73 for people born from 1951 to 1959, and at 75 for people born in 1960 or later, according to Kiplinger.
- QCD limit for 2026: up to $111,000 per person can go directly from an IRA to charity, tax free, from age 70 and a half, according to IRS Notice 2025-67.
- Social Security taxation: up to 85 percent of benefits can be taxable once combined income passes $34,000 for a single filer or $44,000 for a married couple filing jointly, according to IRS Publication 915.
- IRMAA for 2026: Medicare surcharges start when 2024 income passed $109,000 for a single filer or $218,000 for a married couple filing jointly. The standard Part B premium is $202.90 a month, according to Kiplinger.
Your Three Buckets Hold Different Money
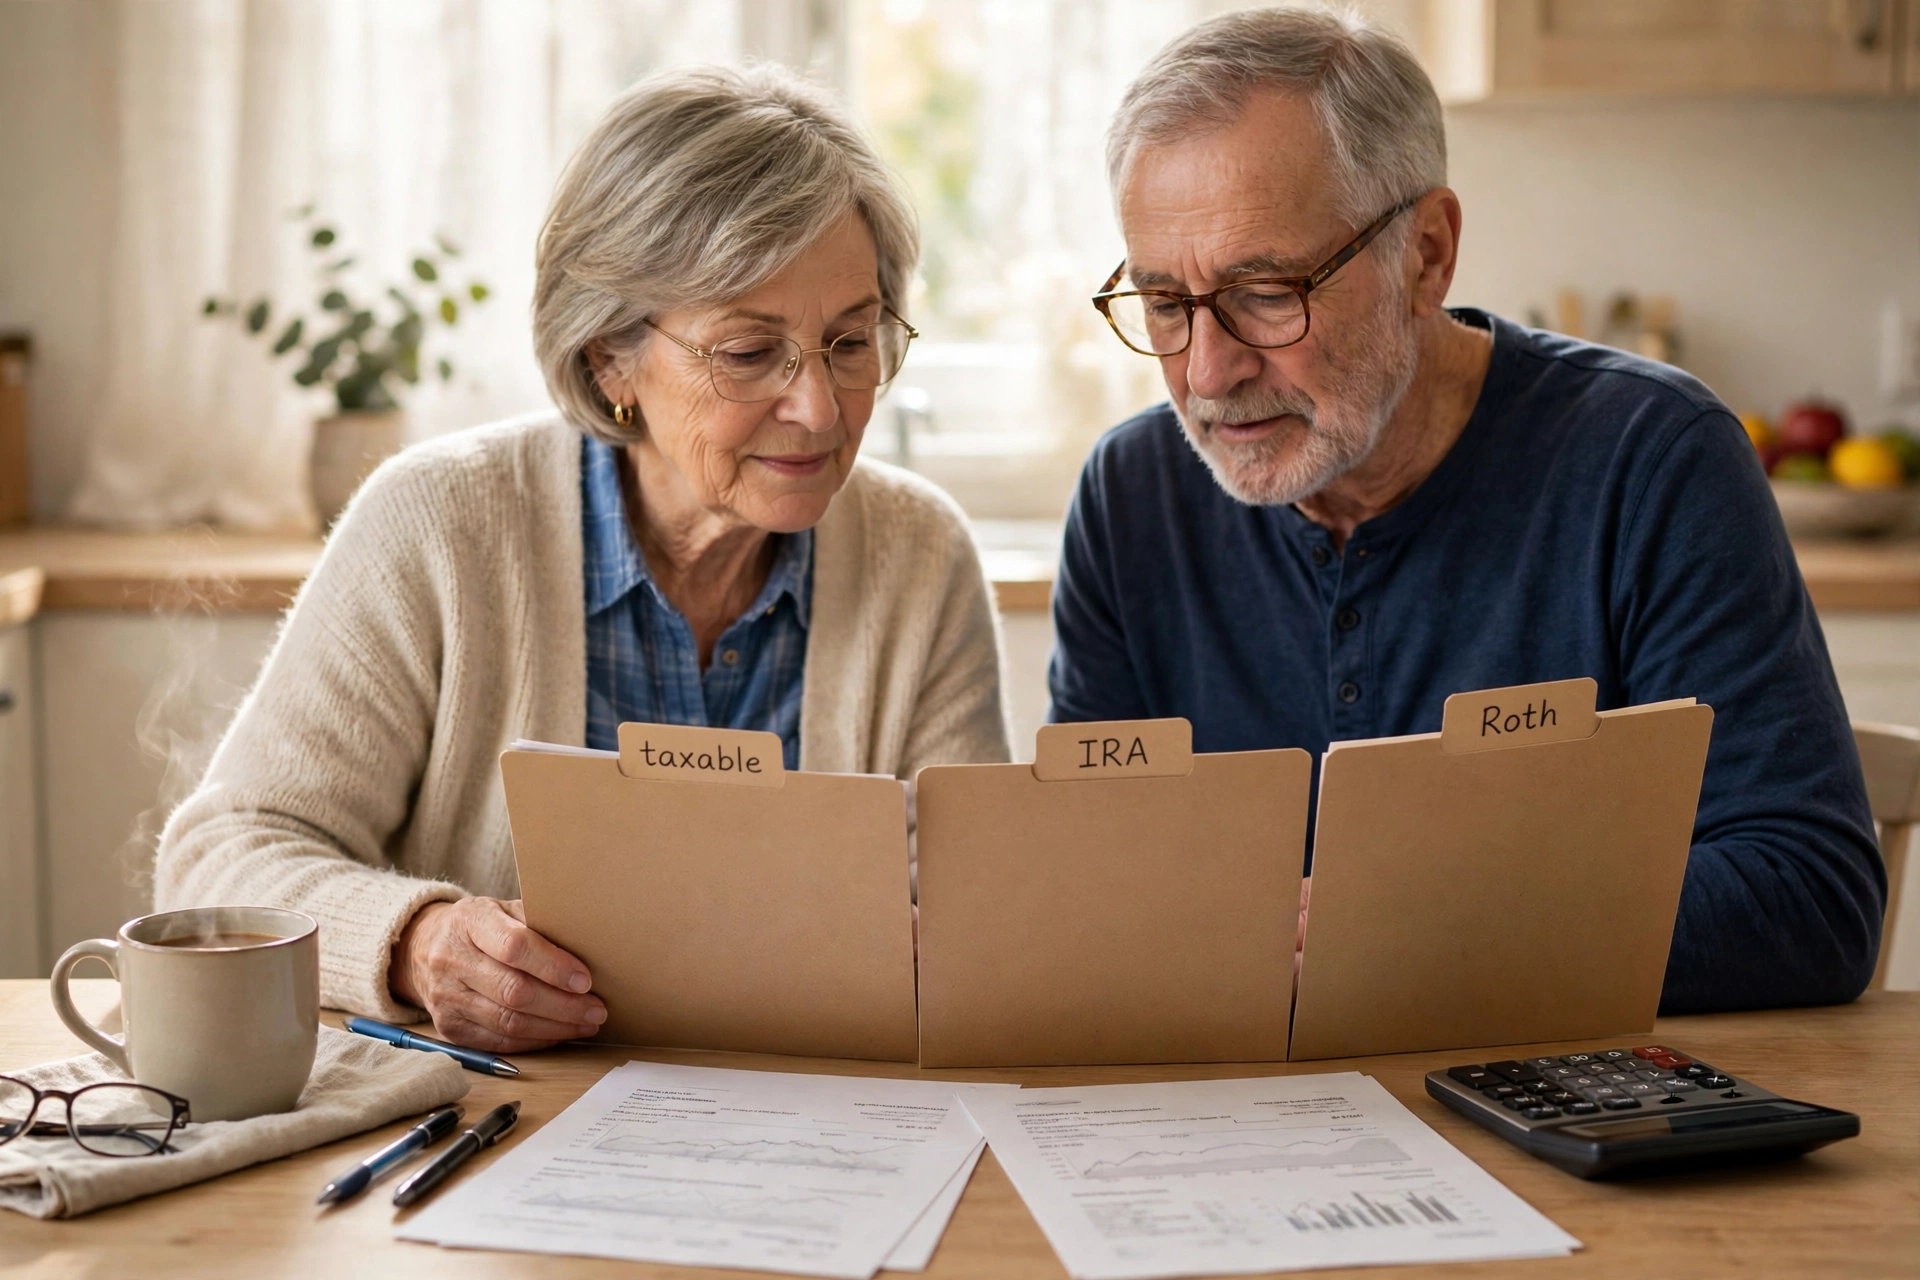
Most retirees hold their savings in three kinds of account, and a dollar in each one is worth a different amount after tax.
The first is the traditional IRA or 401(k). Every dollar that comes out is taxed as ordinary income, at your full marginal rate. Kiplinger gives a clear example: a retiree with $100,000 in a traditional IRA, in the 22 percent federal bracket, has about $78,000 of spending money from it before state tax. Part of that account effectively belongs to the tax authority; the owner just does not know yet how large its share will be.
The second is the taxable brokerage account. Only the growth is taxed, and only when you sell. Gains on assets held more than a year get preferential rates, as low as 0 percent for retirees whose taxable income stays below the thresholds above. You also choose when to realise a gain, which gives you control over the timing of the tax.
The third is the Roth IRA. If the rules are followed, withdrawals are tax free, and Roth IRAs are not subject to required minimum distributions during the owner’s lifetime. That makes the Roth the most flexible money you own, and the last money you generally want to spend.
Owning all three gives you flexibility. Knowing when to draw from each is what turns that flexibility into money.
The Standard Order, and Why Following It Blindly Costs Money
The popular rule of thumb is simple: spend taxable money first, then tax-deferred money, then Roth money last. The logic is sound. Taxable withdrawals cost the least tax, tax-deferred accounts keep growing if you leave them alone, and the Roth benefits most from long tax-free compounding. As a starting point, it is a good rule.
Followed rigidly, though, it can cost you. Kiplinger makes the point with a retiree who spent only from taxable accounts in the early years. His returns looked excellent for several years. Then required minimum distributions began and stacked on top of Social Security and his pension, and his taxes and Medicare premiums ended up higher than under a staged plan. He had not eliminated the tax bill. He had postponed it and possibly enlarged it.
The problem is the empty early years. A retiree who lives only on taxable money can end up with almost no taxable income in the early years of retirement, wasting the 10 and 12 percent brackets that will not come around again. Then, when required minimum distributions start, income bunches together in the later years and pushes the retiree into higher brackets. Often a blend works better: draw just enough from tax-deferred accounts each year to fill a lower bracket, and cover the rest from taxable or Roth money.
Fill the Lower Brackets First: The Roth Conversion Window
The years between retirement and required minimum distributions deserve careful attention. Paychecks have stopped, Social Security may not have started yet, and many retirees sit in the lowest tax brackets they will see for decades. That makes those years a window for deliberate withdrawals or partial Roth conversions.
A Roth conversion means moving money from a traditional IRA into a Roth IRA and paying income tax on the amount moved, in the year of the move. Done in a low-income year, the tax can be charged at 12 percent instead of the 22 or 24 percent that might apply later, once required minimum distributions begin. The converted money then grows tax free, is never subject to required minimum distributions, and passes to heirs tax free.
There is no universal amount to convert. Generating taxes for their own sake is never the goal. The point is to judge the strategy across many tax returns rather than one, and to fill the lower brackets that would otherwise go unused. A conversion also counts as income in the year it happens, so it can push up Medicare premiums two years later, which is why conversions need to be sized with the IRMAA thresholds in mind.
RMDs: The Bill That Arrives at 73 or 75
Required minimum distributions are the government’s way of collecting the tax it deferred while your money grew. Once you reach your RMD age, you must withdraw a minimum amount each year from traditional IRAs, 401(k)s and similar pre-tax accounts. The amount is your account balance on 31 December of the previous year, divided by a factor from the IRS Uniform Lifetime Table. At 73 the factor is 26.5, so a $500,000 IRA produces a required distribution of about $18,868. At 75 the factor is 24.6.
The deadline is 31 December each year, except for your very first RMD, which you can delay until 1 April of the following year. Missing the deadline is expensive: the IRS charges a 25 percent excise tax on the amount you should have withdrawn but did not, reduced to 10 percent if you correct it within two years.
RMDs are what make the early low-income years so valuable. Every dollar you withdraw or convert before RMDs begin shrinks the balance that will drive future RMDs. Every dollar you leave in place grows the future bill.
The QCD: The One Withdrawal That Never Shows Up as Income
For retirees who give to charity, the qualified charitable distribution is the single most powerful withdrawal tool in the tax code. From age 70 and a half, you can have your IRA trustee pay a qualified charity directly, up to $111,000 per person in 2026, and that amount is excluded from your income entirely. It also counts toward your required minimum distribution for the year.
The difference from writing a cheque yourself matters. A normal charitable gift is income first, then a deduction, and the deduction only helps if you itemise. A QCD never becomes income at all. It lowers your adjusted gross income, which can also lower how much of your Social Security is taxed and whether you cross an IRMAA threshold. A married couple with separate IRAs can each make a QCD, for up to $222,000 between them in 2026.
The money must go directly from the IRA custodian to the charity. If it touches your bank account first, the distribution is disqualified and the full amount is taxable. It also has to be completed by 31 December to count toward that year’s RMD and that year’s limit.
Social Security Is Part of the Withdrawal Plan
People often ask for the best age to claim Social Security. That cannot be answered sensibly without seeing the rest of the plan, because claiming and withdrawals are one decision, not two.
Up to 85 percent of your benefits can be taxable. The test uses combined income, which is your adjusted gross income plus any tax-exempt interest plus half of your Social Security benefits. Below $25,000 of combined income for a single filer, or $32,000 for a married couple filing jointly, none of your benefits are taxable. Between those figures and $34,000 single or $44,000 joint, up to 50 percent can be taxable. Above $34,000 single or $44,000 joint, up to 85 percent can be taxable. These thresholds were written into law in 1983 and 1993 and have never been adjusted for inflation, which means more retirees cross them every year.
In certain income ranges, each additional IRA dollar pulls more of your benefit into taxable income, pushing your effective marginal rate well above your bracket. That is why the withdrawal order matters: an extra $1,000 from a traditional IRA can cost far more than $220 in tax if it also drags another $850 of Social Security into taxable income.
Delaying Social Security while living on IRA withdrawals can help on several fronts at once. It shrinks the balance that will drive future RMDs. It replaces fully taxable IRA income with benefits that are at most 85 percent taxable. And it locks in a larger cheque: benefits grow 8 percent for each year you wait past full retirement age, up to age 70, and a surviving spouse can keep that larger cheque if it is the bigger of the two. Delay is not right for everyone; health and cash needs matter. But it shows why claiming and withdrawals should be planned together.
Medicare Premiums: The Two-Year Lookback That Punishes One Big Year
Medicare Part B and Part D premiums rise at higher incomes through surcharges known as IRMAA, the income-related monthly adjustment amount. For 2026, the surcharge applies when the modified adjusted gross income on your 2024 return passed $109,000 for a single filer or $218,000 for a married couple filing jointly. The standard Part B premium for 2026 is $202.90 a month. The first surcharge tier takes it to $284.10, and the top tier to $689.90, with a Part D surcharge of $14.50 to $91.00 on top of the plan premium.
The surcharges work like cliffs. Exceed a threshold by a single dollar and you owe the full surcharge for that tier, for all twelve months. The retiree who takes an extra IRA distribution for a new car, a kitchen remodel or a child’s deposit may see the bill arrive two years later. Roth conversions count too, which is why a conversion sized just under a threshold is worth more than one sized just over it.
The lookback cuts both ways. If your premiums are being set by income from your final working years, you can ask Social Security to use your current income by filing Form SSA-44 and citing work stoppage. Retirement is one of the eight qualifying life-changing events for an appeal.
One gear moves another. A withdrawal affects taxable income. Taxable income can affect Medicare premiums. Social Security can affect taxable income. RMDs can affect both. A plan that ignores any one of them is incomplete.
What Happens When One Spouse Dies, and What Heirs Inherit
Two facts make the survivor’s tax position worse, and both argue for using the low-bracket years while both spouses are alive.
First, when one spouse dies, the survivor generally files as a single taxpayer, with brackets roughly half as wide, while the required minimum distributions stay about the same. The same income that was taxed at 12 percent as a couple can be taxed at 22 percent as a survivor. Drawing down the traditional IRA and converting to Roth while both spouses are alive, at joint rates, is one of the few ways to soften that blow.
Second, traditional IRAs left to adult children must generally be emptied within 10 years under the SECURE Act, often during the heirs’ peak earning years, when their own tax rates are highest. A Roth IRA left to the same heirs is also emptied within 10 years, but the withdrawals are tax free. That makes the Roth the better account to leave behind.
A Worked Example: $60,000 a Year, and No Federal Tax
Here is what the pieces look like together, using the verified 2026 figures. Take a married couple, both 63, retired, with no pension and no Social Security yet. They need $60,000 a year to live on. They hold $400,000 in a traditional IRA, $300,000 in a taxable brokerage account with a $200,000 cost basis, and $200,000 in a Roth IRA.
They withdraw $32,200 from the traditional IRA. That is ordinary income, but the 2026 standard deduction for a married couple filing jointly is also $32,200, so their ordinary taxable income is zero. They take the remaining $27,800 from the brokerage account. Because a third of that account is growth, about $9,267 of the sale is a long-term gain. Their total taxable income is $9,267, all of it capital gain, and the 0 percent capital gains rate for a married couple filing jointly covers taxable income up to $98,900 in 2026. Federal income tax: zero.
The Roth stays untouched, growing tax free, and the traditional IRA balance falls by $32,200 a year, which shrinks every future RMD. In the same low-income years, they could also convert part of the traditional IRA to Roth at the 12 percent rate, paying a small tax now to avoid a larger one later. The example assumes no other income, no state tax and no itemised deductions, and the figures change if any of those assumptions change. But it shows the point: the order you withdraw in can be worth thousands of dollars a year, and the cheapest years to act are the ones before RMDs and Social Security begin.
The Bottom Line
Retirement income works best when you stop asking how to pay the least tax this year, and start asking how to manage taxes over your entire retirement, and your spouse’s and heirs’ lives too. The plan has four moving parts: draw from taxable accounts first, but not exclusively; fill the lower brackets with deliberate withdrawals or Roth conversions in the years before RMDs begin; use qualified charitable distributions from age 70 and a half if you give to charity; and plan Social Security claiming and Medicare premiums as part of the same decision, not as separate ones.
You do not necessarily need a more complicated plan. You need a coordinated one, built before withdrawals are forced on you and revisited every year. The 2026 figures are already published, the window before RMDs is already open, and the cheapest tax years of your retirement may be the ones you are in right now.
Figures in this article come from the sources linked in the text: Kiplinger, 8 November 2026, for the withdrawal framework, the $100,000 account example, the RMD ages, the 10-year inherited IRA rule, the IRMAA lookback and Form SSA-44, and the 8 percent annual increase for delaying Social Security; IRS Revenue Procedure 2025-32 for the 2026 tax brackets, standard deduction and capital gains thresholds; IRS Publication 590-B and the IRS RMD FAQs for the RMD factors, deadlines and penalties; IRS Notice 2025-67 for the 2026 QCD limit of $111,000; IRS Publication 915 and 26 U.S.C. section 86 for the Social Security taxation thresholds; and the Centers for Medicare and Medicaid Services fact sheet of 14 November 2025, as reported by Kiplinger, for the 2026 IRMAA brackets and Part B premium. This article is general information, not tax advice; individual circumstances differ, and a tax adviser should be consulted before acting.
Frequently Asked Questions
What is a tax-efficient retirement withdrawal plan?
It is a year-by-year plan for which account you draw from first, taxable, tax-deferred or Roth, so that your total tax across your whole retirement is as low as possible. The order matters because each account is taxed differently, and withdrawals also affect Social Security taxation and Medicare premiums.
What order should I withdraw from my retirement accounts?
The usual starting order is taxable accounts first, then tax-deferred accounts such as traditional IRAs and 401(k)s, then Roth accounts last. But following that order rigidly can waste the low tax brackets in your early retirement years and bunch income together later, once required minimum distributions begin. A blend, drawing just enough from tax-deferred accounts each year to fill a lower bracket, often works better.
At what age do required minimum distributions start?
At 73 for people born from 1951 to 1959, and at 75 for people born in 1960 or later. The amount is your account balance on 31 December of the previous year divided by a factor from the IRS Uniform Lifetime Table, 26.5 at age 73 and 24.6 at age 75. Missing the 31 December deadline triggers a 25 percent excise tax, reduced to 10 percent if corrected within two years.
What is a qualified charitable distribution, and how much can I give in 2026?
From age 70 and a half, you can have your IRA trustee pay a qualified charity directly, up to $111,000 per person in 2026. The amount is excluded from your income entirely, counts toward your required minimum distribution, and can lower how much of your Social Security is taxed. The money must go directly from the IRA custodian to the charity.
How much of my Social Security can be taxed?
Up to 85 percent of your benefits can be included in taxable income. The test uses combined income: adjusted gross income plus tax-exempt interest plus half of your benefits. Below $25,000 single or $32,000 joint, none of your benefits are taxable. Above $34,000 single or $44,000 joint, up to 85 percent can be taxable. These thresholds have never been adjusted for inflation.
How do withdrawals affect my Medicare premiums?
Medicare Part B and Part D premiums rise through IRMAA surcharges when your income from two years earlier crosses a threshold. For 2026, the surcharge starts at $109,000 of 2024 income for a single filer or $218,000 for a married couple filing jointly. The surcharges are cliffs: one dollar over a threshold costs the full surcharge for that tier. If your premiums reflect income from your final working years, you can appeal on Form SSA-44 by citing work stoppage.
About the Author
Chris Tzitzis
Chris Tzitzis has spent 10+ years explaining personal finance, taxes, investing, and crypto in plain language. Chris turns fine print into clear, verifiable steps, covering IRS relief programs, retirement contribution rules, and life and car insurance, so readers can check eligibility, limits, and costs for themselves. Chris’s guides focus on what is actually true, what applies, and where to verify it, rather than on promises or shortcuts.
More from Insight Bullion